 Live
A revolution in retail investing is underway in India. India had around 237.7 million demat accounts at the end of August 2026, with about 3.27 million accounts added during the month. The monthly SIP investment amount stood at around 31,961 crore in July 2026.
However, SEBI data also shows that the number of individual equity derivatives traders declined from 98.1 lakh in FY25 to 78.6 lakh in FY26, a reduction of about 20%. However, the decrease in the number of players in F&O has not resulted in any better results for those who stayed back. About 87.7% of individuals suffered losses in FY26. Their net loss was around ₹91,685 crore.
These numbers highlight an important distinction: access to the market is only the first step. Understanding risk, choosing suitable products and having a clear investment plan matter just as much. In this blog post, we will go through the pre-investment checklist that should be followed before entering the Indian stock market.
Define your financial goals
Before you open a demat account to invest or start a SIP, you should ask yourself: Why are you investing?
The goal can be anything from buying a house and funding your child’s education to building a retirement corpus and more. The difference matters enormously because the goal can influence the investment product, time horizon and level of risk you may be able to take.
To achieve your goals, the investment instrument you choose must align with your financial goals and risk appetite. Write them down. Assign a rupee value and a timeline to each; everything that follows later on will be based on achieving this.
Build an emergency fund
This is the step that most new investors skip in their excitement to begin their investment journey. It’s also one of the most common reasons behind investors redeeming their investments at a loss when they need the money.
Therefore, keep a liquid emergency fund that covers at least 3 to 6 months of your household expenses. If your monthly expenses are ₹50,000, you need ₹1.5 to 3 lakh sitting in a savings account or a liquid mutual fund before you invest in any long-term investment instrument. Thus, in any emergency, you have a buffer, and you don’t have to sell your long-term investments.
Define your risk profile
In 2025, SEBI carried out a massive investment survey of 90,000 households in 400 cities and 1,000 villages. The result was quite surprising: nearly 80% of Indian families prefer capital preservation over higher returns. While it’s wise to be cautious, it’s also a bad idea to be too cautious, as your investments could end up losing ground to inflation over time.
So, think about whether you’re a conservative investor (one who wants to keep his capital safe), a moderate investor (one who’s willing to take some risks for more gains), or an aggressive investor (one who’s willing to take high risks to gain higher returns). This helps you determine the proportion of your portfolio you should allocate to different segments like equities, debt instruments or safe-haven assets.
Have insurance
This is an aspect most investors often neglect, and they shouldn’t. Term insurance and health insurance aren’t products to buy after building a corpus; they are prerequisites for building one.
Think about it this way: If you are the only breadwinner in your family, and something happens to you, your investments may not be enough to secure your family’s financial future. So, a term insurance policy will provide your family with decent cover, and they will not have to sell off your long-term investments during a crisis.
Similarly, a medical emergency without health insurance can wipe out your years of investment returns in one hospitalisation. So get health coverage and insurance for yourself and your family before you set up your first SIP. These are not an investment. They are protection.
Understand tax implications
Taxes are definitely not something that you think of post-investment. When you begin to invest, taxes form one of the parameters upon which you base your investment. The latest taxation levied on investments for FY 2025-26 is:
● Equity STCG: When you sell equity mutual funds or stocks which have been held for less than 12 months, tax is levied at 20% on all short-term capital gains.
● Equity LTCG: LTCG exceeding Rs 1.25 lakh per year are to be taxed at 12.5%, as long as your holding period of the investment is beyond 12 months.
● Debt mutual funds (post April 1 2023): All gains are treated as short-term capital gains and taxed at your applicable income slab rate, irrespective of the holding period.
● Fixed deposit: Your FD interest gets added to your total annual income, and tax is levied according to your slab rate.
● PPF, EPF, ELSS: Eligible investments and contributions can qualify for deductions under Section 80C, up to a total amount of ₹1.5 lakh. But these exemptions were applicable only under the old tax regime.
Therefore, tax planning should not be associated only with the month of March, but rather be an annual habit of a smart investor.
Align your investment horizon to your product
One of the most common mismatches in Indian retail portfolios is between how long someone plans to stay invested and the product they’ve actually chosen. For example, equity mutual funds and direct stocks are often suited to long-term investors, as equity prices can be volatile over shorter periods.
Parking short-term savings in equity because the market is doing well is a trap. Markets can fall sharply in weeks and take months to recover. Thus, investors often follow this:
● Short-term investment horizon: Liquid funds, short-term FDs, ultra-short duration funds.
● Medium-term investment horizon: Debt mutual funds, balanced hybrid funds.
● Long-term investment horizon: Equity mutual funds, direct stocks, real estate.
Check whether the platform is SEBI-registered
In recent years, there has been a surge in the number of unregulated apps and platforms that offer guaranteed returns with no accountability. Therefore, before you begin your investment journey, confirm whether the broker is registered with SEBI. This is non-negotiable.
You can verify this with the help of the broker’s SEBI Registration Number (e.g., INZ000), which is available at the footer of their website and cross-verify it on the official SEBI website to confirm that the broker is legally authorised to deal with your capital.
If you invest through a broker that is not registered with SEBI, it carries several risks, such as not being eligible for any legal recourse through SEBI or SCORES if funds are misused, or potential conflicts of interest between you and the platform, etc. Additionally, it also carries a high risk of your KYC and financial information being misused.
Never put all your investments in one asset class
Diversification is one of the oldest principles in investing, and it remains one of the most violated by Indian retail investors who tend to concentrate heavily in one sector or product because it has recently performed well.
By diversifying your portfolio across a mix of equity, debt, precious metals, and international funds, you can minimise concentration risk. It is not about equal allocation, but about thoughtful allocation, based on your investment objectives, risk profile and investment horizon.
The traditional rule of thumb for portfolio allocation is to keep (100 (minus) your age)% in equity and the remaining in debt. The composition gradually changes to more secure debt instruments as you get older. For example, a 30-year-old with a long horizon might hold 70% equity and 30% debt, while a 60-year-old would hold 40% equity and 60% debt.
Know when to stay put
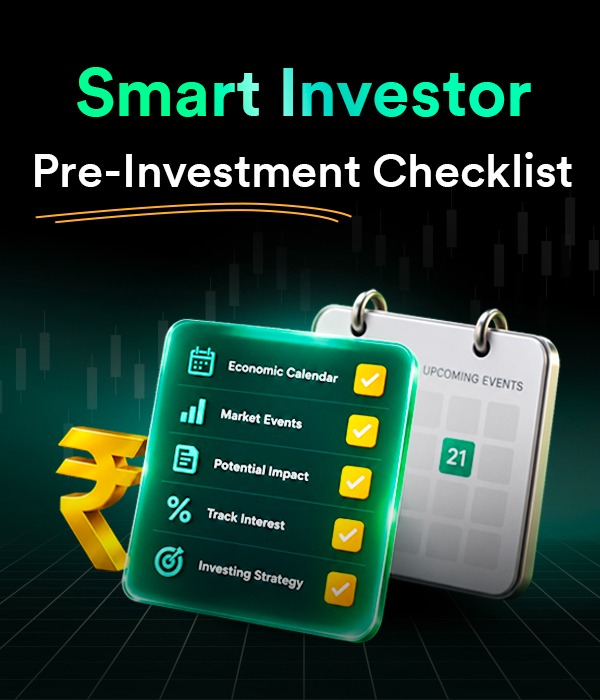
Every year, certain events move markets dramatically, like the Union Budget, RBI Monetary Policy Committee (MPC) meetings, quarterly earnings seasons, global data releases, and elections. A smart investor tracks the economic calendar to stay informed, not to time the market.
Tracking upcoming stock market events can help you avoid making emotionally driven decisions during short-term volatility. For example, when the RBI cuts or hikes rates, banking and real estate stocks react and when the budget announces changes to capital gains or sectoral incentives, specific funds and stocks move. Thus, understanding why markets move is different from predicting when they will move.
Long-term investors should view short-term market-moving factors through the lens of their investment objectives and strategy. They shouldn’t make hasty decisions based on headlines or short-term news, but rather focus on changing realities.
Check the cost structure
Costs compound against you just like returns compound in your favour. Even a 1% fee can consume a significant portion of your net returns over a long-term investment horizon. Understanding the true cost of an investment helps you assess how much of your gross return you ultimately retain after fees, expenses and taxes.
Here are some costs to watch out for to ensure that your portfolio’s yield is not compromised: Total Expense Ratio (TER) in mutual funds (direct vs regular plans), exit loads for early withdrawals, demat and trading charges (brokerage, AMC, DP charges), and statutory taxes.
Understanding the true cost of an investment ensures that the returns on your investments actually end up in your bank account, not as administrative and brokerage fees.
The bottom line
A checklist is only useful if you actually use it. The goal is not to turn every investment decision into a lengthy research project, but to create a simple filter that stops impulsive moves and keeps you aligned with your plan.
Therefore, before every new investment, run through this checklist. When something is unclear or doesn’t feel right, treat that as a signal to pause, not to push through and evaluate it. Over time, this discipline becomes your edge. You can miss some short-term gains, but you may also avoid many costly mistakes.