 Live
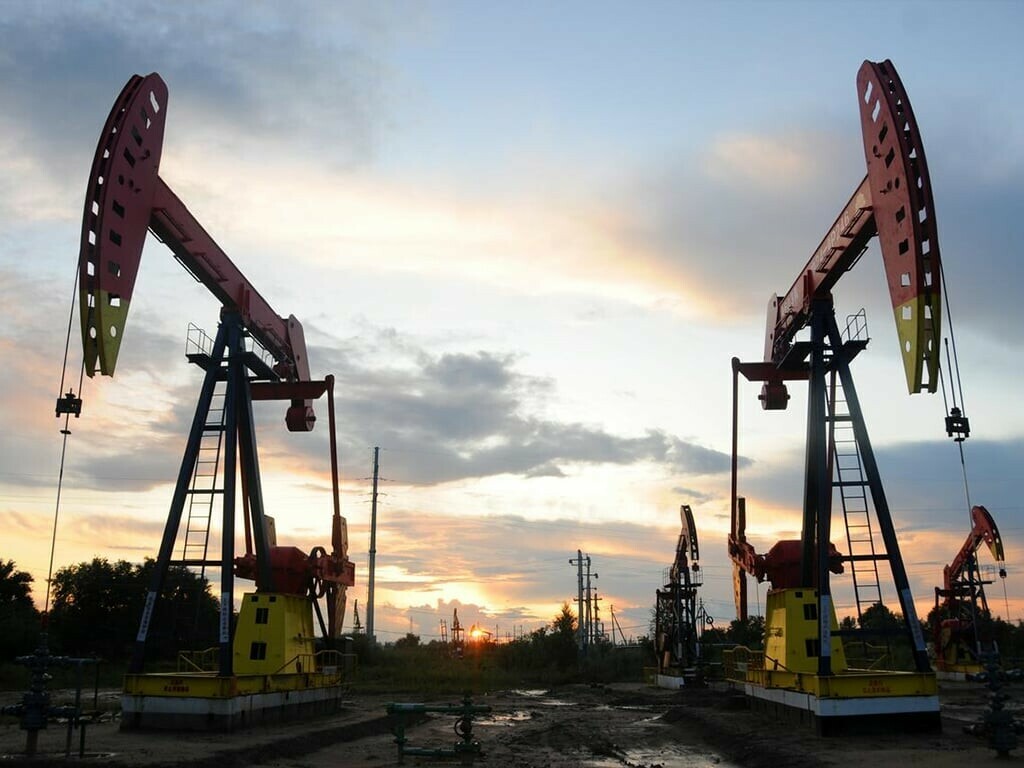
Oil prices reversed course and fell over 2 per cent after the government as per data showed US refiners ramped up output, easing worries of a supply crunch, and as traders took cues from a drop in the equities market.
Brent crude was down $2.41, or 2.4 per cent, at $109.52 a barrel at 12:05 a.m. ET (1605 GMT), while US West Texas Intermediate (WTI) crude fell $2.5, or 2.2 per cent, to $1 09.85 a barrel.
- Orient Cables Eyes Rs 3,500 Crore Revenue By FY30
- Bangladesh Resumes Indian Wheat Purchases as Black Sea Disruptions Lift Prices
- Central Railway Recovers Rs 140 Crore In Ticket Fines
- Cosmic CRF Unit Bags Rs 25.94 Crore Combined Orders
- Arivihan in Talks to Raise Rs 96 Crore at Rs 570 Crore Valuation
Brent settled below WTI on Tuesday – the first time since May 2020 and was still unusually trading at a discount due to strong export demand and tightening US crude stockpiles.
US crude inventories fell by 3.4 million barrels last week, government data showed, as refiners boosted output in response to tight product inventories and near-record exports forced US diesel and gasoline prices to record levels.
Capacity use on both the East Coast and Gulf Coast was above 95 per cent, putting those refineries close to their highest possible running rates.
“While on the face of it, the report was extraordinarily bullish, they (refiners) are racing to put more refined products on the market, there’s a refiners response,” said John Kilduff, a partner at Again Capital LLC.